The unique experience and financial freedom promised by Rubies Bank
Feature Highlight
Rubies Bank was launched as Nigeria’s fully digital banking platform to help to accelerate the process of financial inclusion.
In March 2019, a six-year-old financial technology (fintech) savings marketplace, Raisin, acquired MHB-Bank of Frankfurt, Germany. The Berlin-based fintech said it acquired the 46-year-old bank – which has been its long-time provider of banking services in Germany – to expand its operations.
Raisin essentially bucked the trend of banks acquiring fintech companies. According to CB Insights, a technology market intelligence platform, 18 fintechs were acquired by 10 top American banks, including Goldman Sachs, between 2013 and 2018.
The disruption in the banking sector caused by the rapid encroachment of fintechs into the financial services sector is the reason many banks are either developing their own digital services or acquiring fintechs. While the battle ensues between traditional banks and fintechs, advancements in technologies are enhancing access to various financial services, especially via mobile devices.
But so far, close to two billion people still do not have access to financial services. They don’t have bank accounts and they cannot access credit, among other services. According to the 2017 Global Findex data, 1.7 billion adults are financially excluded. The 2018 Access to Financial Services Survey conducted by the Enhancing Financial Innovation and Access (EFInA) shows 36.8 percent (36.6 million) of adults in Nigeria are financially excluded.
Financial exclusion has been identified as one of the factors responsible for keeping people in extreme poverty. This is why the Central Bank of Nigeria (CBN) has set a target for the country to achieve 80 percent financial inclusion rate by 2020. In other words, this will bring the financial exclusion rate down to 20 percent.
But to achieve this target, traditional banking methods alone would be insufficient. There are certain locations, especially in rural areas, where brick and mortar banks would be unable to penetrate. Innovations such as digital banks and mobile money have to catalyse the achievement of financial inclusion.
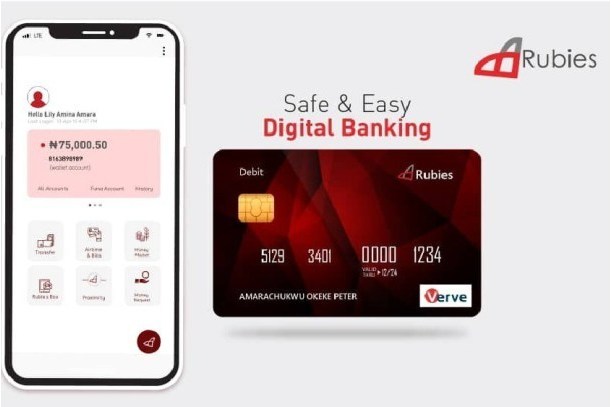
Rubies Bank was launched as Nigeria’s fully digital banking platform to help to accelerate the process of financial inclusion. A digital bank is not the mobile app of a bank. Rather, it is a boutique bank that provides financial services through digital channels. Digital bank customers can access an array of banking services, including cash deposit, withdrawal, transfer, payment of bills, loans and investment management. All these services are provided through digital channels such as mobile and web app, USSD codes, POS terminals and ATMs.
Unlike ALAT, another digital bank, and other quasi-digital banks in Nigeria, Rubies Bank has a unique feature that allows anyone to become an “independent banker”. As an independent banker, customers earn money whenever anyone they introduce to join the platform performs a transaction. Inter-bank transfers, which traditional banks charge N52 for, cost only N21 on the Rubies Bank’s platform.
This is in addition to other services such as customisable account number, proximity transfer, free customisable debit cards and money request. On Rubies, customers can chat with one another and provide or obtain loans in the digital bank’s money market based on the credit score of the customers on the platform.
A fully digital platform, Rubies Bank offers zero-fee banking services targeted at millennials, the upwardly-mobile professionals and small and medium-scale enterprises. Its open banking architecture enables smooth integration with other fintech companies and financial institutions. Rubies also provides bank-as-a-service. This enables the use of its technology infrastructure by other financial institutions.
Rubies was established by Highstreet Microfinance Bank, an existing financial institution. This is because the CBN has not yet created a specific licence for the establishment of a digital bank. This circuitous approach to establishing a digital bank to promote financial inclusion does not foster innovation neither does it help in achieving the apex bank’s objective of 80 percent financial inclusion by 2020.
No doubt, innovation often precedes regulation. But if innovation must facilitate and solve many of society’s problems, regulators need to be up-to-date with regulations in order not to impede innovation.
Digital banks, like every other innovation, provide speed, convenience and save cost. They eliminate the hassle of going to a bank’s branch, reduce the operational costs of banks and allow customers to have seamless banking experiences. Rubies says it has come “to disrupt and give every individual control of their banking experience as well as financial freedom.”
Daniel Iyanda is a Financial Nigeria Staff Writer
Editor's Note
This article is published under the series Finance and Technology, a new platform of Financial Nigeria magazine, promoted by Simplex Business Solutions Limited. Knowledge leaders in the interception of finance and technology are welcome to contribute to the industry platform. Editorial contributions should be submitted to editor@financialnigeria.com.
Other Features
-
Nigeria’s democratic illogic
Can a country achieve its lofty aspirations when its governance framework is openly contradicted by practice and by ...
-
Analysis of Nigeria’s new virtual asset taxation framework
The framework is technically rigorous and sound, but its success will depend heavily on administrative capacity and ...
-
No free ride: Uber’s African retreat
Nigeria hardly offered Uber a competition-free road. Uber was not even the country’s first ride-hailing ...
-
What will determine the next gold price movements
Gold still has strong bullish fundamentals over the medium term. However, the path toward higher levels is unlikely ...
-
What would make Sidi Ould Tah smile?
After a year in office, Sidi Ould Tah has begun to reshape how the African Development Bank raises money and prepares ...
-
Nigeria’s Paris Club debt deal: A factual rejoinder to Donald Duke
Obasanjo’s credit was never in danger and did not require Duke to vandalise everyone else’s contribution.
-
Where to sell Steam gift cards in Nigeria: Rates, apps and how to ...
See where to sell Steam gift cards in Nigeria, current 2026 Steam card rates, and how to get paid on ...
-
Nigeria is building a sustainable health financing future
Gavi’s US$500 million support will help protect Nigeria’s children over the next five years while ...
-
An analysis of the Executive Order on Virtual Assets 2026
The new presidential executive order addresses a real problem – the cost and risk of regulators working in ...


Most Popular News
- Dangote Refinery posts $1.82 billion profit ahead of landmark IPO
- Alliance to End Plastic Waste reports progress on circular economy
- Digital services boom widens global trade gap, UNCTAD says
- AfDB approves $5.1 billion response to energy and fertiliser shocks
- BoE rate hold draws criticism as inflation climbs above 3 per cent
- CBN elevates terrorism financing oversight as key supervisory priority
Quick Search for Upcoming Events